
Disclaimer: Nothing you read here should be construed as investment advice. I do not know your circumstance and so please treat the below as nothing more than what my thoughts are, which are subject to change without notice. Please do your own work and consult your own financial advisor. We may own positions in all stocks, sectors and indices discussed and can exit them without notice. You will very likely lose money if you use any information in this post without your own due-diligence.
Regulatory Information.
Indian Markets.
There is a very uneasy dichotomy in the Indian markets right now. There is a section of the market which is in a complete bull grip while there is another section that is undergoing an almost cathartic range bound action.
We know which is which. The question really is why is this happening?
It’s really a function of multiple headwinds on one side and multiple tailwinds on the other and we had discussed this in detail in the last note.
Essentially its comes down to just one thing. Low earnings growth.
What’s worse is not that the earnings growth is low but the more important variable i.e. future growth perception is probably at the weakest for this set of stocks led primarily by the top 10-20 Nifty names.
So essentially we are now in what’s called the “stock pickers market”. To be fair all markets are stock picker’s market but what they mean by this is that there are phases when the entire market does well i.e 70% or more do well and there are phases when only a select set 20-30% of the market is going up.
What decides which type of a market it is? There are two factors:
Growth
Excess Liquidity
When there is only growth but not much excess liquidity we get the narrow market that we are in. When there is growth plus excess liquidity i.e. lot of capital chasing stocks we get a broad based bull market.
What’s wrong with liquidity? Two main things:
FII selling - this is beaten to death now - FIIs have been mostly selling than buying - so the incremental liquidity from this camp is net negative. Best not to get into the reasons - again that’s beaten to death too.
Promoter selling - IPOs, QIPs, OFS - a lot of supply coming through via this route
Both of these are eating any excess incremental liquidity coming primarily from domestic mutual funds.
One other reason for subdued net liquidity is retail investors seem pretty disillusioned by both their returns over the last couple of years and the constant war newsflow on the one hand and the AI doom newsflow on the other. Unless the newsflow improves expect a continuation of the more of the same and the slow grind to continue for the broader markets.
How to play the Indian Market now (or ever)?
In this season, things have been fairly easy for those who chase earnings vs those who chase value.
Value has mostly turned out to be trap. So far. But we all know its a pendulum. One of these days there will be a sharp mean reversion move and the set of stocks under-performing today will out-perform. It’s guaranteed. In that phase what’s doing well today will under-perform. This is the nature of the market.
So what’s the problem? The problem is that we as investors have a need to be right all the time so we end up being right only once in a while and that too purely by chance. This need makes us want to chase what’s working and often at precisely the wrong time. This need is what makes us think markets are complicated.
What’s the solution? The solution is to have an anchor. Decide what is your anchor? Is it to chase growth, is it to chase value? Do you find comfort in large caps or small caps? Once you decide stick to it. Know that markets are cyclical - it will come in your favour eventually if your process is right. You need to stand your ground to be able to harvest the reward when your time comes and have the ability to sit tight when the market are counter cyclical to your strategy. The best of investors have done this - Buffett in 1999 as a vivid example that comes to mind.
The solution is not to jump ships when there is trouble. It will leave you worse off.
Now some of us are growth oriented, small/mid cap investors - we went through shit in the 12 months leading to Feb-March’26. Only those who stuck around could enjoy the run up from April until now. There was no genius who held large caps till March’26 and entered small caps from 1st April. If there is i am happy to learn.
So we should stop chastising those who are following their process, who have done well over the long term just because they are not doing well recently.
Now i have no need to say all this as growth + small cap which happens to be where i operate is working well, but i have spent enough time in the markets to know that everything here is seasonal. We’ve to take the good times and the bad times and accept the net result.
Global Markets.
There is just one durable theme in the global markets right now. It is AI or is it SI now?
The entire space really is in a flux and no one really knows where it is headed. But i saw a chart which i thought was pretty apt in terms of where the opportunity in AI is going to be.
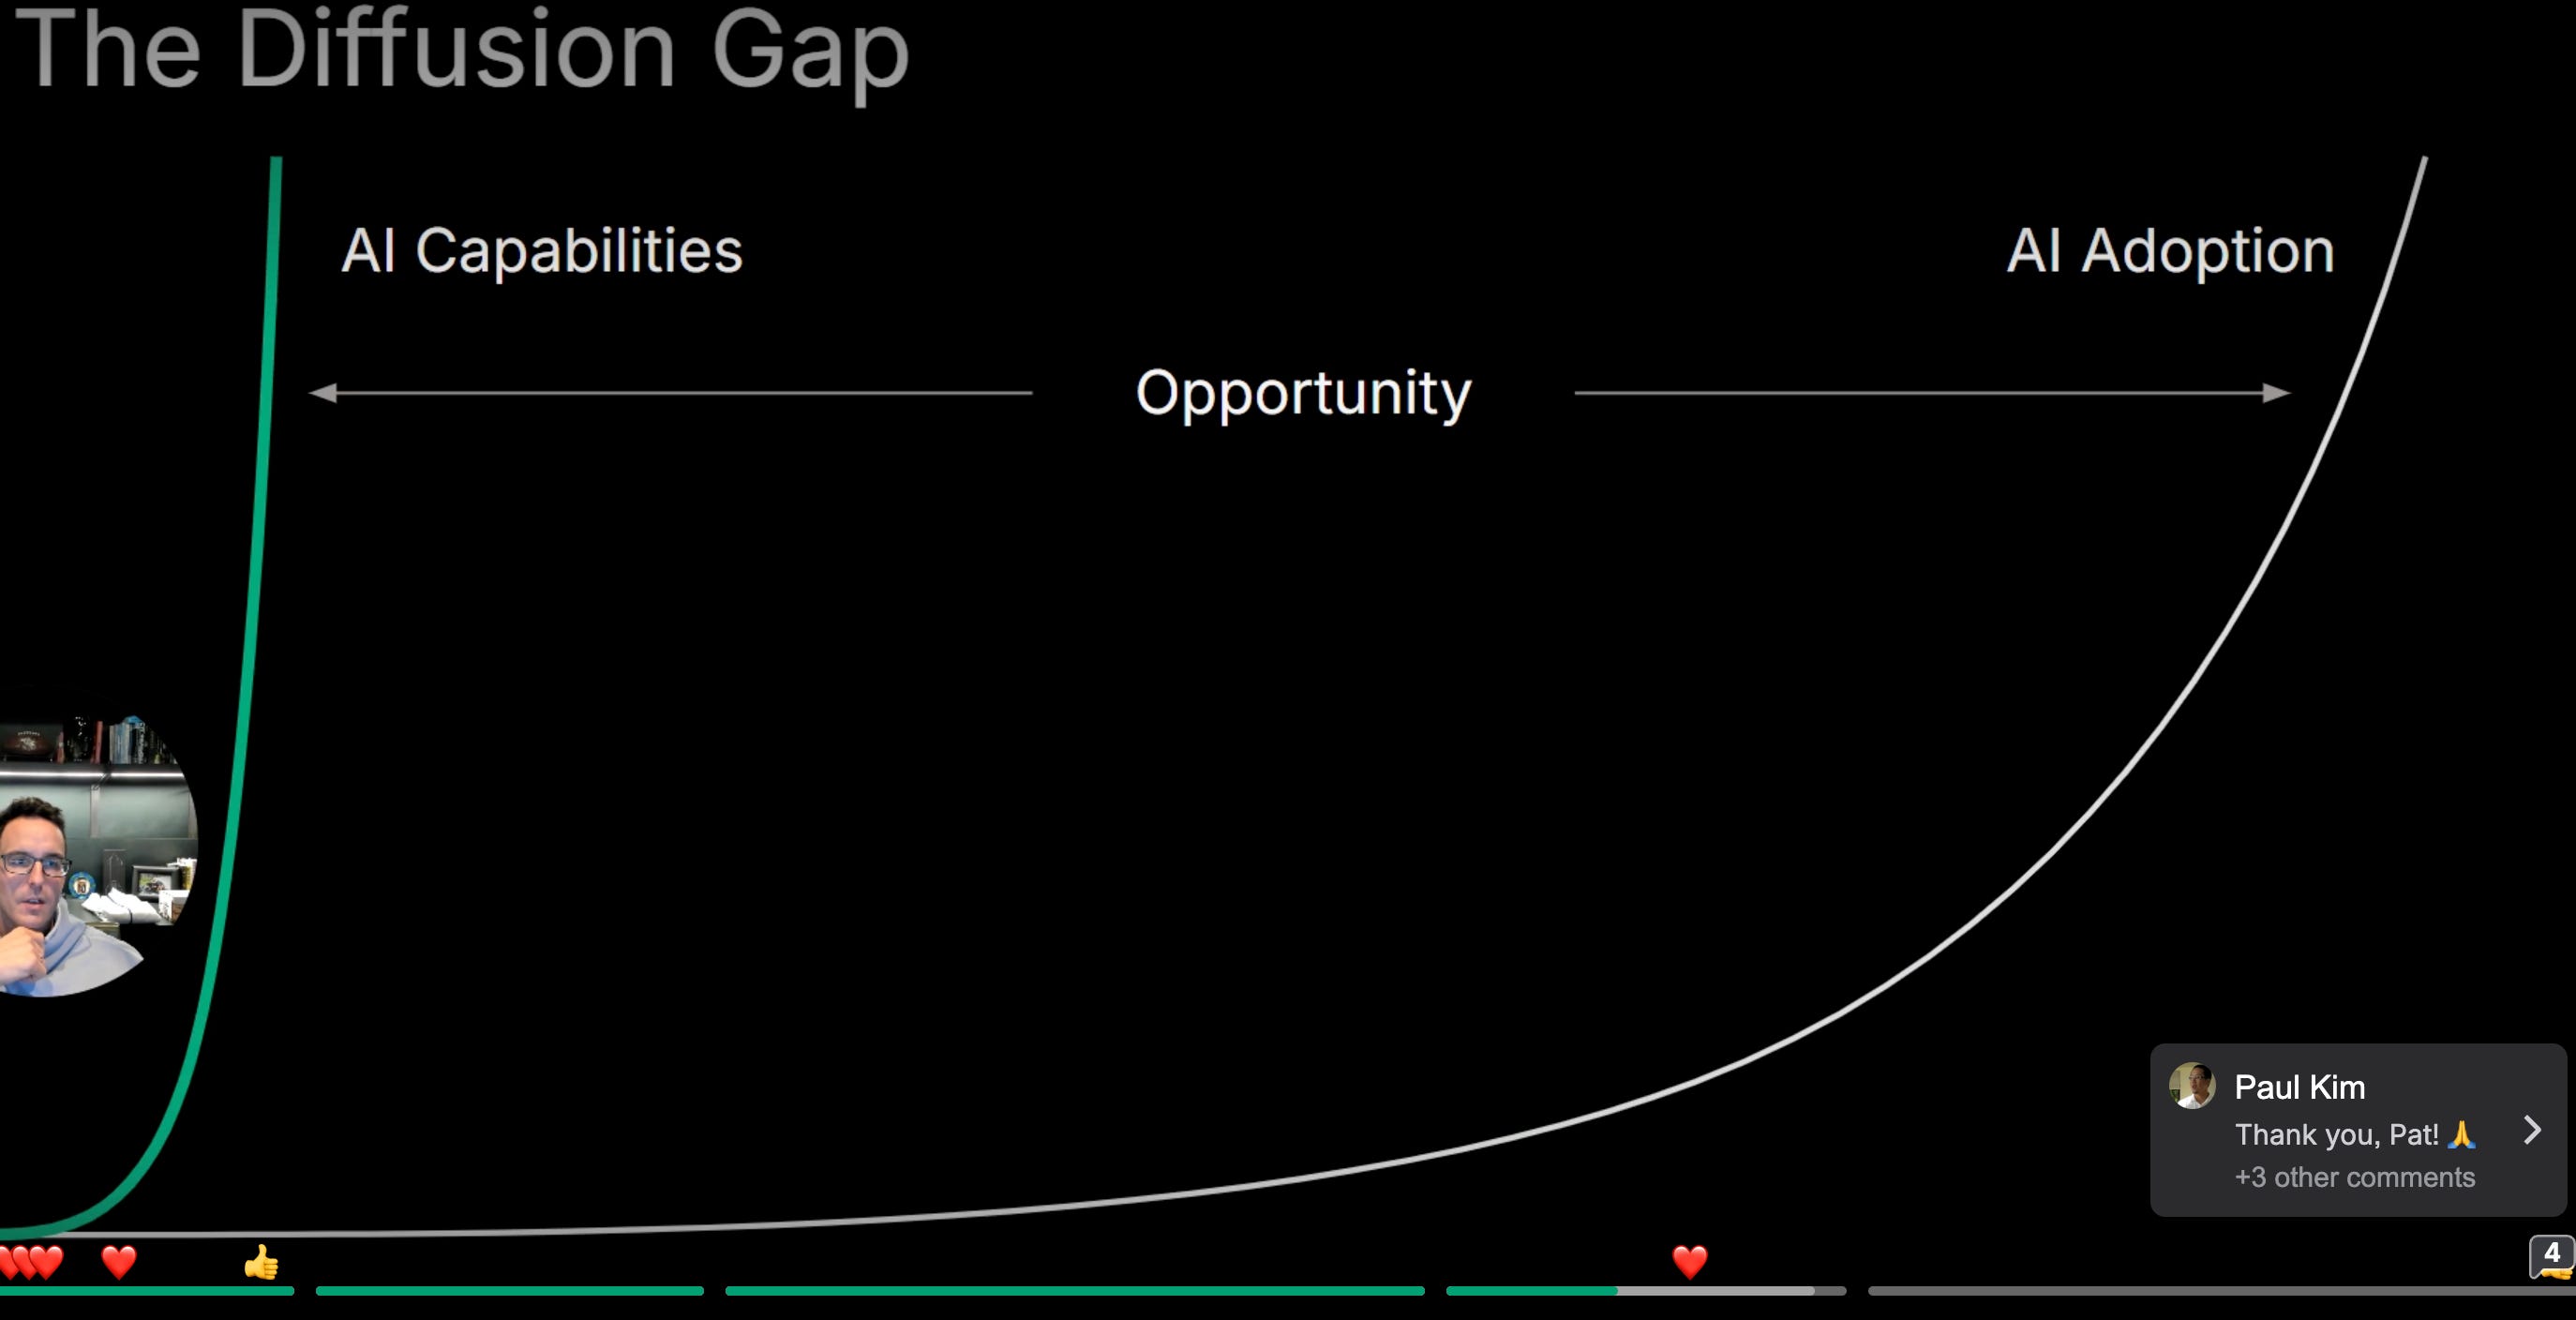
It’s a great video and i suggest you watch it. Link in the tweet below.

Essentially what the graph says is that while AI capabilities are already fairly advanced, over the next few and many years the real money will be made as these capabilities diffuse through the economy and to the individuals.
Given we dont know where this whole AI thing is headed, the best strategy would be to bet on a basket of stocks across the AI layer. I love this 5 layer cake diagram that Nvidia popularized and keep referring to it whenever i think about the whole AI theme.
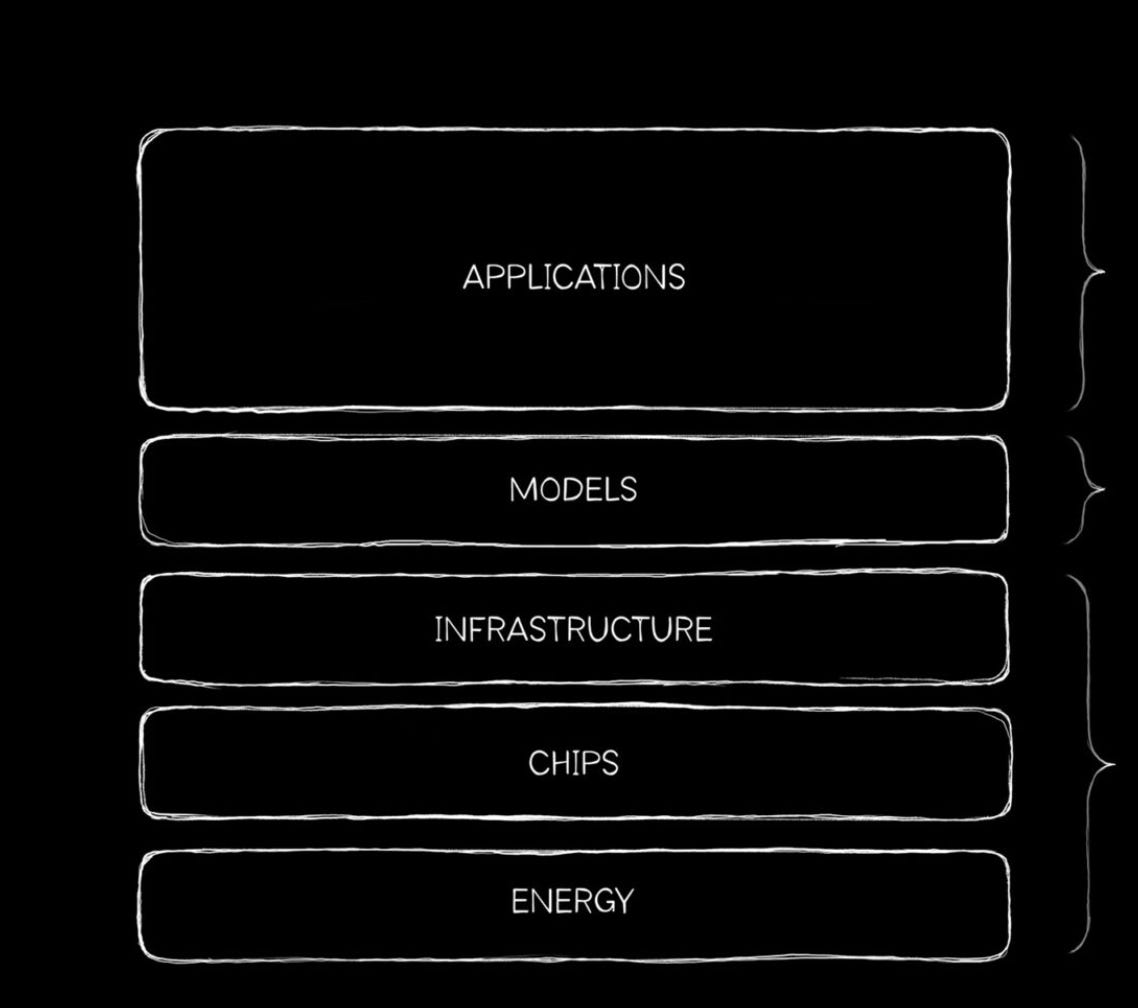
We need to actively monitor the developments at each of these layers to be able to make sense of and find the future opportunities in this space and incrementally adjust the exposures. Each of these layers is under-going massive changes and represents big opportunities on their own.
There are several Indian companies riding this same wave as ancillary companies. For those who are not comfortable allocating to global equities they are a good proxy to play the AI theme.
Crude.
The other big variable out there as far as India is concerned is the price and volatility of crude oil. While what’s happening right now is not ideal for India, I doubt if crude oil has seen a better scenario globally than the one if the last few months and yet the price of crude finds it hard to stay sustainably above $100.
That to me is one of strongest indicators that the price action seems to give. The line of least resistance for crude is down. I know that most articles and most analysis is arguing for a much higher crude but i dont completely agree to the thesis as the reasons for crude to move up are artificial, not structural. The whole situation can be reversed in a matter of days when its suitable for those involved. The market knows this and hence the resistance for a higher crude price. If the reasons were structural, crude today should have been at $150 or higher.
Another angle to look at this is, ten years back crude at $120 was crisis for India, today our economy has grown massively from that base, so many alternative sources have come up and inflation adjusted crude even at $100 in real terms is much lower and much more manageable for us than in the past. Of course the lower the better but i don’t really agree with the fear-mongering every time crude moves above $100. Today’s $120 is not the same as it was for India ten years back.
Earnings Digest.
Given regulations, I want to talk about sectors with good earnings rather than specific stocks. Here are the themes that stood out in Q1:
AI and its ancillaries in india which is primarily power led have taken a bit of a backseat this quarter after a great run, but i expect this theme to pick up post the natural consolidation and digestion of the up-move. As earnings continue to improve on the back of robust global order execution and new order flows one can expect Q2 to be good too in which case the sector should start firing again.
I think the out and out best performing theme post Q1 has been Pharma. The entire CDMO pack right from large, mid, small and micro caps have fired both on the earnings as well as the price front. The concalls point to a fairly strong medium term outlook for this entire space.
The other surprise this quarter was speciality as well as commodity chemicals. But this was primarily led by inventory gains on higher crude prices. Some of them have no doubt demonstrated volume growth too where the earning’s momentum may continue to sustain - however the rest of the pack is going to be a play on crude indirectly. Given that the crude continues to be strong so far the prices are holding up but i would be a bit careful on these names where its only realization led and not volume led.
Auto and auto ancillaries posted great numbers but didn’t do much this quarter in terms of price - reasons being two-fold - already priced in for the quarter and in Q2 and Q3 the high base will start catching up. If there are any surprises where the growth surprises even on a high base for some of these names then we could be in for a PEAD in many of these names.
Semis and chip EMS players may start showing some earnings traction as plants have begun to be commissioned. This is an area one should keenly watch.
I had mentioned about mid cap IT in the last note - most of them have done fairly well. I think the game remains in the mid and small cap IT space who are nimble enough to pivot to AI while the larger incumbents will find it difficult to manage the drag of the large legacy services business.
Private defence players - most of them had posted a good Q1 and if the run continues in Q2 we could see many of them breaking out to new orbits.
Aerospace seems to be coming of age in terms of execution starting to show up. Numbers have been good in Q1 and so was the commentary across many companies. The prices have run up so one will need to carefully watch the Q2 numbers which will decide the trajectory.
Textiles - I had mentioned in the last note - the catalysts here should be the US, UK and EU FTAs coming into play. Still in a watch for execution mode as they come out of the tariff mess and start to take advantage of the FTAs. This could be a medium to long term one time re-rating play.
Overall i am looking forward to a fairly robust Q2.
Let’s hope that the geopolitics settles down and the focus of the market can be 100% on what matters the most - earnings.
Sticking to an investment philosophy is my favourite lesson from this article. Tough, but pays off big in the long run
Hey, good one. The application layer of AI is what I have been thinking on, other layers are sort of easier to figure. Now the problem with that is everyone and their dog is talking of how they are using AI to transform their business, most are either lying or conflating efforts with outcomes.
Not that AI can't or won't transform businesses, it probably will but we are at a nascent stage and it would take time even though adoption of AI is much quicker than other technology shifts. My question is what variables would you use for measuring results in application layer. For example, AI may reduce the time for drug development by 20% and they may improve Pharma RoE significantly but when and how will that be visible in the numbers is hazy. How would you look at this?